

ReSource Pro’s Gene Hugh on FOMO-driven spending, why the partner who knows insurance will outperform the one with better technology, and why the organizations writing eight-figure AI checks without a clear thesis are making a huge mistake.
Key takeaways
- FOMO is not a strategy. And the board presentation won’t save you: Too many insurance organizations are approving AI budgets to demonstrate momentum rather than solve defined problems. Without clarity on whether the goal is cost reduction, productivity gain, new revenue, or client experience, the build/partner/buy decision has no foundation to stand on.
- AI has broken the traditional CapEx/OpEx framework (and most finance teams haven’t caught up): Token costs scale in ways that aren’t visible at contract signing. LLM expenses can move from pilot-sized to enterprise-sized without triggering the capital approval processes that would normally apply. Until organizations develop a clean framework for how AI spend is classified and measured, the return calculations will keep coming up wrong.
- Modular architecture is a financial decision, not just a technical one: Organizations that lock into a single integrated AI ecosystem are betting the technology landscape will stay stable long enough to justify the commitment. Building in components, such as evaluating the LLM, orchestration, and interface layers independently, preserves the optionality that moves fast enough to matter in two years.
- The partner who knows insurance will outperform the one with better technology: A solution that handles 80% of standard cases efficiently still leaves the 20% of edge cases that carry disproportionate risk and cost in insurance. Domain knowledge, which includes understanding the actual workflow, the regulatory constraints, the exception handling, is what closes that gap, and it can’t be licensed from the same place as the model.
- The CFO’s job has changed from gatekeeper to informed partner: A finance leader who can only evaluate AI investment against a clean one-to-one KPI will consistently underfund the right initiatives and approve the wrong ones. Understanding what the technology is actually doing — well enough to evaluate gray-area cases with uncertain timelines — is now part of the role.
- Separate operational experimentation from innovation investment, and govern each differently: Operational AI initiatives should have defined success criteria, a timeframe, and a clear shutdown trigger. Genuine innovation investment operates more like R&D, with longer-dated and harder-to-measure returns. Conflating the two, or writing eight-figure checks without a thesis for either, is where organizations lose both money and credibility.
- Insurtech valuations are more differentiated than the market suggests: Grade-A players are still commanding high valuations. The opportunity is in companies that have found a real niche but haven’t yet reached a standalone stride. It’s about finding where the right acquirer creates the one-plus-one-equals-three outcome. As LLMs commoditize, what holds durable value is the knowledge, context, and domain expertise layered on top of them.
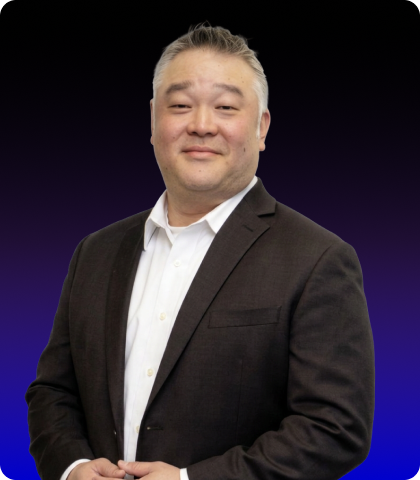
Gene Hugh leads global finance and strategy at ReSource Pro, where he oversees accounting, FP&A, tax, treasury, legal, and M&A.
Before joining ReSource Pro in 2025, he spent 15 years at Intercontinental Exchange navigating major acquisitions and enterprise-wide technology initiatives. That experience gave him an especially grounded perspective on what disciplined investment in emerging technology actually looks like versus what it tends to look like in practice.
The Insurance Lead spoke with Hugh about how insurance organizations should be framing their AI investment framework, where the build/partner/buy framework still holds, and what the CFO’s role needs to become.
The Insurance Lead: Insurance companies are under real pressure to show AI is more than a cost center. From a finance and strategy standpoint, what’s unique about insurance’s relationship to AI, and how should a retail broker, carrier, or MGA be framing AI investment — is it CapEx, OpEx, or something that requires its own category?
Gene Hugh: I think there’s still, even now, a significant element of FOMO driving a lot of these decisions. Competitors are doing it, leadership needs to show the board they’re investing in AI. But they’re doing it without the forethought, the diligence, the design work, and what I’d call a use case review of what they’re actually trying to get out of it. Is it cost reduction? Productivity gain? New client revenue? New client experience? That clarity has to come before anything else, or the investment doesn’t have a foundation.
On the CapEx versus OpEx question specifically, that’s actually one of the things AI has genuinely complicated in ways that the traditional technology model didn’t. With hardware-based machine learning, it was relatively clean: you buy GPUs, it’s CapEx, you have developers who build the model, done. That world made sense to finance organizations.
Now, with enterprise-level AI (e.g., Claude, Copilot, the OpenAI ecosystem) the cost structure is different and often less visible. Token costs can be buried inside vendor relationships. LLM expenses can scale in ways that aren’t apparent at contract signing.
Whether AI spend is capital or operating isn’t settled accounting, and it has real implications for how finance evaluates the return. Most organizations haven’t developed a clean framework for this yet, and that’s a problem that falls squarely in the CFO’s lap.
The build/partner/buy framework has been around in corporate strategy for decades. What does it look like when you apply it specifically to AI investment in insurance, and where does it break down or require new thinking?
The framework itself still applies. You’re still doing a cost-benefit analysis, still asking how long it takes, how much it costs, what you get at the end. What’s changed is the complexity of those inputs and the speed at which the answers go stale.
The design question matters more now than it ever did. People think AI is an easy button: you prompt it and it does everything for you. That is not reality.
At ReSource Pro, we’ve been on this AI journey and we’ve learned a lot going through it.
The design of how AI works within a mix of software, infrastructure, LLMs, and orchestration is critically important. And that complexity is where the framework starts to break down if you treat it as a simple three-option decision. You have to understand what you want, how you want to design it; and then, within that design, which components you build, which you buy, and which you partner for.
The other place the framework requires new thinking is governance. When you give individuals AI tools that make it genuinely easy to build and deploy applications, you’ve expanded the scope of what IT has to vet and review in ways that didn’t exist before. Someone in operations builds something useful, wants to roll it out company-wide, and suddenly you have security review, compliance questions, and resource demands that the technology organization wasn’t designed to handle. Having a governing model for what gets deployed — and who decides — isn’t bureaucracy. It’s how you prevent a productivity tool from becoming an organizational distraction.
One of the risks of the build path is that by the time an organization is live with something it built internally, the underlying technology has already moved. How do you think about obsolescence risk embedded in a build decision?
This is where I see organizations making an AI investment mistake that will cost them significantly in the next 24 months. If you commit to a single integrated AI package — locked into one ecosystem, with everything delivered together — you’ve made a bet that the technology landscape will look roughly the same when you need it to. That bet is increasingly unlikely to pay off.
My recommendation is to think in components. What is the LLM doing? What is the
orchestration layer doing? What is the interface doing? If each piece can be evaluated and swapped independently, you preserve flexibility without starting over. That’s not just good engineering; it’s sound financial planning. The organizations that componentize their AI architecture now will have dramatically more optionality in two years than the ones that went all-in on a single integrated solution, however polished that solution looked at the time.
The partner option often looks lower-commitment, but partnership agreements in technology can become surprisingly sticky. What should insurance organizations be evaluating before they sign, and what exposures do they tend to underestimate?
Trust, longevity, history, and a genuinely client-centered viewpoint — those are the things that matter most, and they’re harder to evaluate than the technology itself. The technology will change. We know things will evolve and potentially be displaced in whatever timeframe is coming. What you need to know is whether the partner understands your business and your pain points, because if they don’t, the solution might be technically competent and still miss the mark.
The 80/20 problem is real here. A solution that handles 80% of standard cases efficiently still leaves 20% edge cases, and in insurance, those edge cases carry disproportionate risk and cost. If you’re still spending the same amount of time and attention on the difficult 20%, the ROI math often doesn’t work out the way it looked in the vendor presentation. The partner who understands the actual workflow, the regulatory constraints, the exception handling, will consistently outperform the one with stronger technical credentials and weaker industry context.
I’d also say that vetting the partner’s own competitive position matters. Is there a technology innovation coming that will put this partner into the obsolescence category? Is there another player that’s going to displace them in the next six months? Some of that is a calculated risk every organization has to accept. But you should go in with your eyes open about it.
A lot of AI investment decisions in insurance are being made at the business unit level, which creates redundant tools, competing vendors, and no coherent data strategy. What’s the CFO’s role in bringing discipline to that without becoming the person who kills innovation?
This is exactly the tension, and I don’t think there’s a clean answer. But there is a better approach. The CFO has to be a partner across the organization, not a gatekeeper at the end of the process. That means understanding what the technology is actually doing, not at a developer level, but well enough to evaluate gray-area cases where the home-run model isn’t available.
When a CTO or CIO is making the case for an investment that has meaningful upside but uncertain timelines, the CFO needs to understand the thesis well enough to make an informed call. You can’t just wave it through or kill it on ROI grounds.
What I’d push for is a concerted effort to understand what’s being deployed across the organization and what each deployment is actually trying to do. Everybody is getting a Copilot license and going to town. That’s diffusion; it’s not a strategy. It makes individual productivity gains almost impossible to measure at the enterprise level because the spend is so fragmented. Finance can’t evaluate what it can’t see, and if AI spend is happening in dozens of business units without coordination, you’ve effectively made it invisible to the people who are supposed to be managing capital allocation.
How should insurance organizations be measuring the return on AI investment within their framework, and what are the most common mistakes in determining an investment’s potential?
The biggest mistake is insisting on a clean one-to-one KPI for every dollar spent. Some of the value is direct and quantifiable: cycle time reduction, headcount efficiency, claims handling speed. Some of it is softer: better client experience, improved decision quality, faster response to market conditions. A CFO who only funds the former will consistently underfund the right initiatives and approve the wrong ones.
What I’d recommend is separating operational experimentation from genuine innovation investment. For operational initiatives, like automating a specific process, improving a specific workflow, you should have defined success criteria, a timeframe, and a mechanism for tracking trajectory. If you’re not getting there, shut it down. That discipline keeps costs rational and keeps the organization honest.
For true innovation investment, the analysis is different. These are more like R&D: you’re placing a bet on future capability and the return is longer-dated and harder to measure. The mistake is conflating the two or spending significant money on “AI innovation” without a clear thesis. I’ve seen organizations write eight-figure checks with no coherent strategy behind them, primarily to demonstrate to the board they’re not falling behind. That is a very, very large mistake.
As insurtech valuations have shifted and more AI-native companies are coming to market, do you see a window opening for retail brokers, carriers, and MGAs to acquire AI capabilities they’d previously have had to build or partner for?
Valuations have come down from where they were six to 12 months ago, partly because there are more entrants in the VC market and partly because a lot of companies haven’t performed the way their funding rounds implied they would. But the grade-A players are still commanding high valuations. It’s those specific insurtechs that have found the niche, found the technology, found the path to real growth. So it’s not a uniformly better buyer’s market; it’s a more differentiated one.
What we look for is the moat: the technology, the process, or something that differentiates a company from the market, even if that company hasn’t yet hit the stride it needs as a standalone. That’s where the one-plus-one-equals-three conversation happens: they’re good on their own, but with the right partner or acquirer behind them, they can be significantly better.
My longer-term view is that LLMs will become a commoditized product. Everyone touts the LLM as the brain behind whatever insurtech they’re looking at, but it’s available to everyone. The price will come down.
What won’t commoditize is the knowledge, the context, the experience; the layer on top of the model that actually understands the problem being solved. That’s where durable value will sit, and that’s what acquirers should be evaluating.
Frequently Asked Questions
Q: What is the biggest mistake insurance organizations make in AI investment?
A: The biggest mistake is approving AI budgets without a clear thesis: investing to demonstrate momentum to the board rather than to solve a defined problem. Without clarity on whether the goal is cost reduction, productivity gain, new revenue, or client experience, the build/partner/buy decision has no foundation.
Q: How should insurance organizations classify AI spending: CapEx or OpEx?
A: There is no settled accounting answer, and that ambiguity is itself the problem. Unlike hardware-based machine learning, enterprise AI costs, including token costs buried in vendor relationships, can scale in ways that aren’t visible at contract signing. Most finance organizations haven’t developed a clean framework for classifying AI spend, which means return calculations consistently come up wrong.
Q: How does the build/partner/buy framework apply to AI in insurance?
A: The framework still applies, but the inputs are more complex and go stale faster. The more important shift is architectural: organizations need to think in components — evaluating the LLM, orchestration layer, and interface independently — rather than committing to a single integrated ecosystem. That componentized approach is both sound engineering and sound financial planning; it preserves optionality as the technology evolves.
Q: What is obsolescence risk in AI, and why does it matter for insurance?
A: Obsolescence risk is the danger that an organization builds or buys an AI solution that the underlying technology has already moved past by the time it goes live. Organizations that lock into a single integrated AI package are making a bet that the technology landscape will remain stable long enough to justify the commitment. That bet is increasingly unlikely to pay off in a two-year window.
Q: How should insurance organizations evaluate AI partners?
A: Technology credentials matter less than domain knowledge. A solution that handles 80 percent of standard cases efficiently still leaves 20 percent of edge cases. And in insurance, those edge cases carry disproportionate risk and cost. The partner who understands the actual workflow, the regulatory constraints, and the exception handling will consistently outperform the one with stronger technical credentials and weaker industry context.
Q: What is the CFO’s role in AI investment decisions?
A: The CFO needs to function as an informed partner across the organization, not a gatekeeper at the end of the process. That means understanding what AI is actually doing well enough to evaluate gray-area investments with uncertain timelines. It’s not just approving initiatives with clean KPIs and rejecting everything else. Finance can’t evaluate what it can’t see, and fragmented AI spend across business units effectively makes capital allocation invisible.
Q: How should insurance organizations measure ROI on AI?
A: By separating operational experimentation from genuine innovation investment and governing each differently. Operational AI initiatives should have defined success criteria, a timeframe, and a clear shutdown trigger. Innovation investment operates more like R&D, with longer-dated and harder-to-measure returns. Conflating the two — or writing eight-figure checks without a thesis for either — is where organizations lose both money and credibility.
Q: Who is Gene Hugh?
A: Gene Hugh leads global finance and strategy at ReSource Pro, overseeing accounting, FP&A, tax, treasury, legal, and M&A. Before joining ReSource Pro in 2025, he spent 15 years at Intercontinental Exchange navigating major acquisitions and enterprise-wide technology initiatives. He spoke with The Insurance Lead about AI investment frameworks, obsolescence risk, and the evolving role of the CFO in insurance organizations.